Table of Contents
s
tocks, ETFs or index funds: which one should you choose? For most beginners, the honest answer is a broad, low-cost fund as the core of a portfolio, with individual stocks as an optional extra. This guide explains how the three differ, what the evidence says about picking stocks and active funds, what Nigerian investors can actually buy, and how to decide. It is general education, not financial advice.
The Short Answer
If you want to invest and not spend your evenings researching companies, a broad index fund or index-tracking ETF is usually the simplest place to start. If you enjoy studying businesses and can afford to lose the money, individual stocks can be a small, separate experiment. Many people do both, with most of their money in funds.
What Each One Is
| Individual stocks | ETFs | Index funds | |
|---|---|---|---|
| What you own | A share of one company | A basket of investments that trades on an exchange | A fund that copies an index such as the S&P 500 |
| How you buy | Through a broker or investing app | Through a broker or investing app, like a stock | Directly from the fund company or through a platform |
| Diversification | None on its own | Often broad, but depends on the ETF | Broad by design |
| Main cost | Trading fees | A small annual fee plus trading costs | A small annual fee |
| Best for | Investors who want to research companies | Flexible, low-cost access to a basket | Hands-off, long-term investing |
The three aren’t strict opposites. An ETF is a fund that trades on an exchange like a stock, and an index fund is a fund that tracks an index. Many ETFs are index funds, so “ETF or index fund” is often a question about how you buy it, not what you own.
Amazing Beach Scenery & Relaxing Ocean Sounds
What the Evidence Says About Beating the Market
The most useful test is how professionals do. S&P Dow Jones Indices’ SPIVA scorecard compares active funds with their benchmark index. In its Year-End 2025 edition, 79% of active large-cap US stock funds underperformed the S&P 500 over the year, and the share was higher over longer periods.
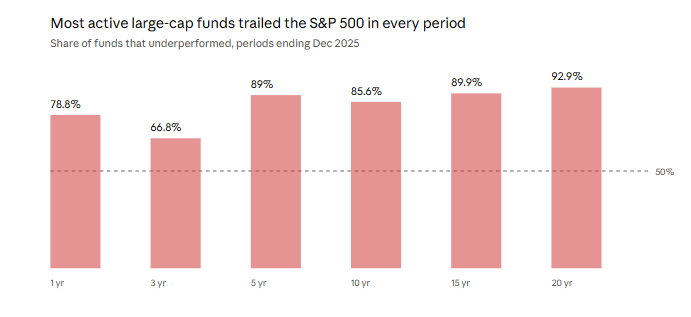
This measures active funds, not individual stock picks, but it shows how hard beating the market is, even for full-time professionals. It also doesn’t mean index funds always win in every year or every category. It means that, over long periods, a low-cost index fund beat most of its active competitors.
How to Choose
Answer these three questions:
- How much time do I want to spend? Funds take almost none. Stocks need ongoing research.
- How much can I afford to lose? A single stock can fall sharply or fail. A broad fund spreads that risk.
- What am I investing for? For goals many years away, low-cost diversification is usually the sensible default.
A common approach is core and explore: build the core of your portfolio from broad funds, then, if you want to, put a small slice you can afford to lose into individual stocks.
What Nigerian Investors Can Buy
You have two main routes.
Funds listed on the Nigerian Exchange (NGX). The NGX publishes a list of listed exchange-traded products, including Stanbic IBTC ETF 30 and Vetiva Griffin 30 ETF, which track the NGX 30 index of the exchange’s largest and most liquid companies, plus sector funds, the Lotus Halal Equity ETF, a sovereign bond ETF, and NewGold. You buy them through a licensed stockbroker. One guide reports management fees of about 0.5% for Stanbic IBTC ETF 30 and 0.6% for Lotus Halal, and says some funds require a minimum of 1,000 units while others can be bought a unit at a time, so check each fund’s current minimum and fees.
US and global funds through an app. Registered apps let you buy US-listed ETFs and fractional shares with naira. We explain how this works, and what it costs, in our guide to how to invest in US stocks from Nigeria.
Whichever route you choose, remember the exchange rate. Investing in dollar assets means the naira-dollar rate affects your return in naira, in either direction.
The Costs That Quietly Matter
Fees compound just like returns do. Here is a hypothetical example, not a forecast. Suppose $10,000 earns 7% a year before costs for 20 years. With a 1% annual fee, it grows to about $32,000. With a 0.1% annual fee, it grows to about $38,000. That is a gap of roughly $6,000 from fees alone.
When you compare options, look at the annual fund fee, any trading commission, and the currency conversion cost if you are buying foreign funds.
Common Mistakes
- Chasing last year’s winner. Top performers rarely stay on top.
- Owning several funds that hold the same thing, which adds fees without adding diversification.
- Ignoring fees because they look small.
- Investing money you’ll need soon in assets that can fall.
- Trusting “guaranteed” returns or unregistered platforms.
- Trying to time the market instead of investing steadily.
A Simple Way to Start
- Write down what the money is for and when you’ll need it.
- Build a small emergency fund first, so you aren’t forced to sell investments in a crisis.
- Choose one broad fund as your core, and compare its fee with at least one alternative.
- Invest a fixed amount on a regular schedule instead of trying to time the market.
- Review once or twice a year, and avoid reacting to every headline.
Frequently Asked Questions
Is an ETF better than an index fund? Neither is automatically better. Many ETFs are index funds, so the real choice is usually about how you buy and what it costs.
Are stocks too risky for beginners? Single stocks carry more risk than broad funds because everything depends on one company. Many beginners start with funds and add stocks later.
How much do I need to start? It depends on the platform and fund. Some funds and apps have low minimums, but check fees and minimums before you commit.
Does this apply to investing from Nigeria? Yes, with two extra considerations: the exchange rate if you buy dollar assets, and Nigerian tax rules, which changed in January 2026. Confirm tax questions with a qualified professional.
Is this financial advice? No. This is general education. Consider speaking to a licensed adviser about your situation.